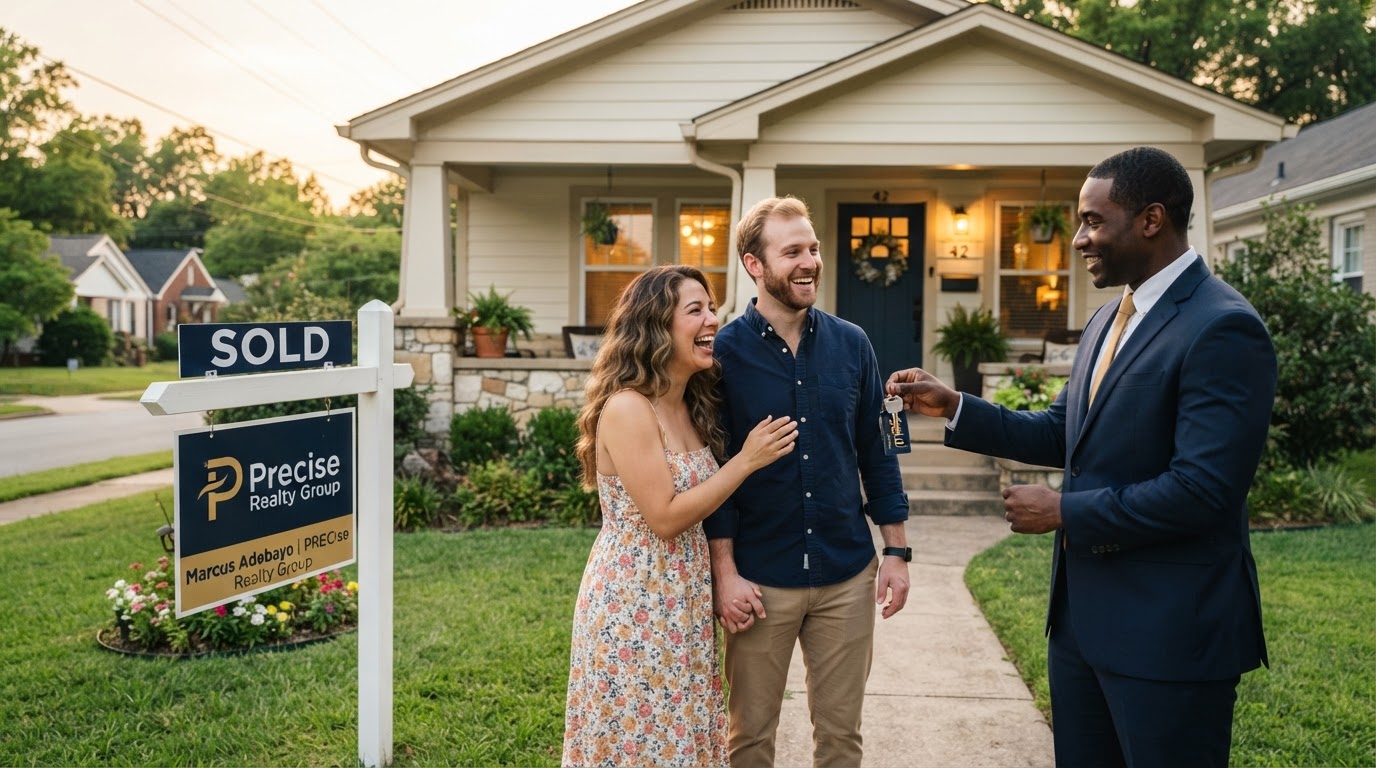
Alabama Homebuyer Opportunity
Down Payment Assistance
You may be much closer to buying a home than you think. Learn how state and local Alabama programs can help cover your down payment and closing costs.
Check Your Down Payment Eligibility in 2 Minutes
Through my partnership with the Greater Alabama MLS and Workforce Resource, you can instantly search over 2,500 national, state, and local homebuyer programs—tailored specifically to Alabama buyers and properties.
Free, confidential search. No credit pull required to view program details and income limits.
Knowledge Is Power
What Is Down Payment Assistance in Alabama?
Down payment assistance (DPA) includes government, non-profit, and private programs designed to help qualified homebuyers cover the upfront cash required to purchase a home. In Alabama, these programs are most commonly administered by the Alabama Housing Finance Authority (AHFA), local city and county community development departments, and designated participating lenders.
Alabama Housing Finance Authority
AHFA Step Up Program
One of Alabama's most popular programs, offering down payment assistance (typically up to 4% of the loan amount) paired with a 30-year fixed-rate conventional or FHA first mortgage for qualified moderate-income borrowers.
- Up to 4% down payment assistance
- Competitive fixed interest rates
- Available statewide across Alabama
Forgivable & Deferred Options
Second Mortgages & Soft Seconds
Subordinate financing provided by state, county, or municipal housing agencies. Many 'soft seconds' accrue 0% interest and forgive a portion of the balance for every year you occupy the home as your primary residence.
- 0% or low interest rates
- Forgivable over time
- Helps bridge the cash-to-close gap
Non-Repayable Homebuyer Grants
Closing Cost & Grant Assistance
Pure grant programs funded through state or local housing partnerships, Federal Home Loan Bank (FHLB) programs, or employer-assisted housing benefits that do not require monthly repayment.
- Funds never have to be repaid
- Applies to down payment or closing costs
- Subject to program availability
Educators, Healthcare, First Responders, Veterans
Community Partner & Hero Incentives
Targeted assistance initiatives created to help teachers, police officers, firefighters, healthcare heroes, veterans, and municipal workers buy homes in the communities they serve.
- Special credit or grant enhancements
- Combined with VA or conventional loans
- Honors public service in Alabama
Unlock Your Front Door
Down Payment Money Is Available
Millions of dollars in homebuyer assistance go unclaimed every year simply because buyers don't know the funds exist.
See If You're Eligible
Shelter & Stability
Explore Greater Birmingham Grants
From Jefferson and Shelby counties to St. Clair and beyond, find assistance programs matching your target neighborhood.
Launch Program FinderBusting Real Estate Myths
Don't Let Down Payment Misconceptions Hold You Back
According to the National Association of REALTORS®, saving for a down payment is cited as the single biggest hurdle by prospective homebuyers. But much of that fear is built on outdated advice.
Myth #1
“I have to put 20% down to buy a home in Alabama.”
Myth #2
“Down payment assistance is only for very low-income families.”
Myth #3
“You can only get assistance if you have never owned a home before.”
Myth #4
“Down payment assistance adds months of delays and red tape.”
Myth #5
“Down payment money has to be repaid immediately if you move.”
Your Roadmap
How to Access Down Payment Assistance
Run the Search
Use Dante's online portal to input basic household details (income, household size, target area) and view every matching program in Central Alabama.
Pair with a Participating Lender
Not all lenders are approved to issue AHFA or specific municipality DPA funds. Dante connects you with trusted local loan officers who specialize in DPA.
Complete Homebuyer Education
Most programs require a HUD-approved homebuyer education course (often completed online at your own pace) to ensure long-term homeownership success.
Shop with Confidence
With pre-approval and DPA reserved in writing, tour homes knowing your exact buying power, cash-to-close requirements, and monthly budget.
Ready to See What Assistance Programs You Qualify For?
Click below to launch Dante Wormley's direct Workforce Resource portal for Greater Alabama MLS. It takes just two minutes and provides a detailed summary of programs matching your profile.
Alabama Real Estate Commission (AREC) Compliance: Dante Wormley is a licensed REALTOR® affiliated with Precise Realty Group LLC (Shannon Wormley, Qualifying Broker), 2700 Corporate Dr, Suite 200, Birmingham, AL 35242. Office: 205-832-5885. Mobile: 205-977-0063.
Real Estate Consumer's Agency Disclosure Act (RECAD): Alabama law requires real estate licensees to provide an explanation of the types of brokerage services available to consumers (single agency, subagency, dual agency, or transaction broker). This website and the Down Payment Assistance search tool provide informational and marketing resources and do not, by themselves, create a fiduciary or client relationship. A written agency agreement signed by both parties is required to establish client representation.
Lending & Program Disclaimer: Dante Wormley and Precise Realty Group LLC are real estate professionals and are not mortgage lenders, mortgage brokers, or financial underwriters. Down payment assistance programs, eligibility guidelines, income limits, interest rates, and funding availability are established and administered by third-party government agencies, housing authorities, and participating mortgage lenders. All loan programs and assistance options are subject to credit approval, underwriting guidelines, and property eligibility. Information provided on this site and through the Workforce Resource / Down Payment Resource tool is deemed reliable but is not guaranteed and is subject to change without notice.
Equal Housing Opportunity & Code of Ethics: Dante Wormley strictly adheres to the Federal Fair Housing Act, the Alabama Real Estate License Law, and the National Association of REALTORS® (NAR) Code of Ethics. Professional service is provided without discrimination based on race, color, religion, sex, handicap, familial status, national origin, sexual orientation, or gender identity.